CGT Other Disposals
This guide explains how to use the My Tax Digital interface to record Capital Gains Tax (CGT) on the disposal of assets other than UK residential property — including cryptoassets, shares (listed and unlisted), and other chargeable assets.
These disposals are reported on SA108 (Capital Gains Summary).
1. The CGT Other Disposals Overview
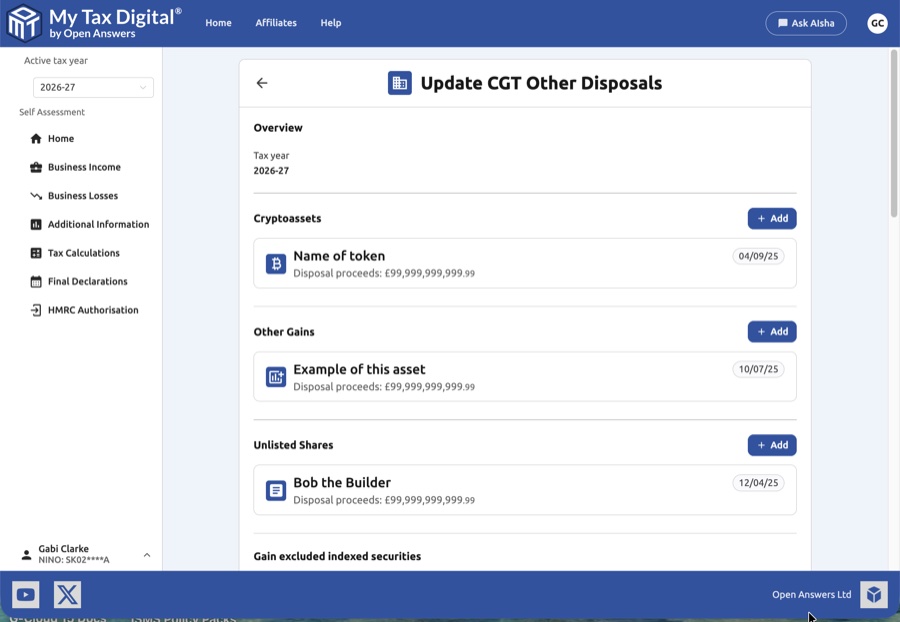
The CGT Other Disposals screen categorises your disposals by asset type.
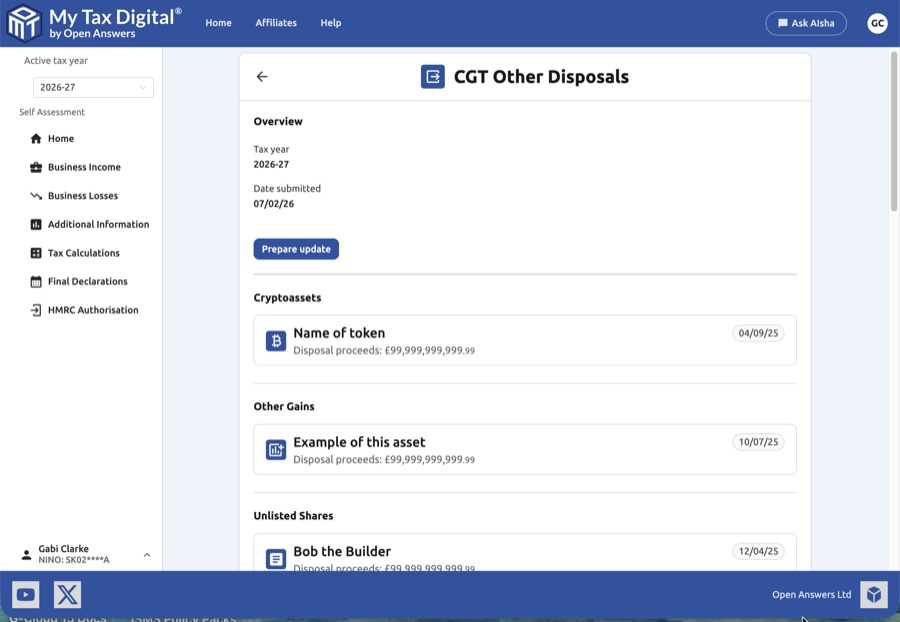
- Asset Categories: The screen is divided into sections for different asset types:
- Cryptoassets: Disposals of cryptocurrency and other digital assets.
- Other Gains: Disposals of other chargeable assets. Each entry has an Asset type field — Listed shares, Other property, Other assets, or Non-UK residential property — so this category also covers quoted shares, unit trusts, OEICs, and other listed collective investments (use Listed shares), not just the "other" examples below.
- Unlisted Shares: Disposals of shares in companies not listed on a recognised stock exchange.
- Existing Entries: Each entry shows the asset name, disposal proceeds, and disposal date.
- Gain Excluded Indexed Securities: A section at the bottom for gains on indexed securities that are excluded from CGT calculations.
- Non standard gains: shown for 2025-26 only. HMRC removed this section from 2026-27 onwards, so it doesn't appear when a later tax year is selected.
- Prepare Update: Click the Prepare update button to enable editing and add new disposal entries.
2. Adding a Disposal
Click the + Add button next to the relevant asset category to open the disposal entry modal.
The fields are the same for each category, except where noted.
| Field | Description |
|---|---|
| Asset type (Other Gains only) | Other property, Listed shares, Other assets or Non UK residential property - see Other Gains guidance below. |
| Number of disposals | How many disposals this entry covers (at least 1). |
| Asset description | A description of the asset disposed of. |
| Token name (Cryptoassets only) | The name of the cryptoasset token. |
| Company name | The company whose shares or asset were disposed of. Required for Unlisted Shares, optional for Other Gains. |
| Company registration number | Optional. Only accepts a UK Companies House format (8 digits, or 2 letters followed by 6 digits) - this is an HMRC requirement, not a My Tax Digital restriction. For a non-UK company, leave it blank. |
| Acquisition date | The date the asset was acquired. |
| Disposal date | The date the asset was disposed of. |
| Disposal proceeds | The total proceeds from the disposal. |
| Allowable costs | The total allowable costs deducted from the proceeds, including the purchase price. |
| Gains with BADR | Gains eligible for Business Asset Disposal Relief, before losses. |
| Gains with INV (not Cryptoassets) | Gains eligible for Investors' Relief, before losses. |
| Gains before losses | The total gain before losses are deducted. |
| Losses | The total allowable losses from the disposal. |
| Claim or election codes | HMRC codes for specific relief claims or elections. The codes offered depend on the asset category and asset type. From 2026-27 this includes Incorporation relief (INC). |
| Amount of net gain / Amount of net loss | The net gain or net loss from the disposal - fill in one, not both. |
| RTT tax paid | Tax already paid through HMRC's Capital Gains Tax Real Time Transactions service for this disposal. |
Unlisted Shares also has fields for gains reported on RTT, gains exceeding the lifetime limit, gains under SEIS, and losses used against general income.
Several disposals in one entry (brokers' schedules)
If you're entering a broker's or platform's schedule as one entry, HMRC asks you to use the date the first asset was acquired as the Acquisition date, and the date the last asset was disposed of as the Disposal date. Set Number of disposals to how many disposals the entry covers.
3. Asset-Specific Guidance
Cryptoassets
Each disposal of cryptocurrency (e.g., Bitcoin, Ethereum, NFTs) is a separate CGT event. Use the pooling rules for fungible tokens — your cost basis is typically calculated using HMRC's Section 104 pool method. You can record each disposal separately, or group them as described under "Several disposals in one entry".
Unlisted Shares
Shares in private (unlisted) companies are valued at market value on acquisition and disposal. You may need a professional valuation if no arm's length transaction occurred.
Other Gains
Select the Asset type that matches your disposal:
- Listed shares — quoted shares, unit trusts, OEICs, and other listed collective investments.
- Other property — commercial property and other property not covered elsewhere.
- Other assets — personal possessions worth more than £6,000 (the chattel exemption), antiques, artwork, collectibles, business goodwill, and any other chargeable asset not covered by another category.
- Non UK residential property — residential property located outside the UK.
4. Finalising Your Submission
After entering all disposals:
- Submit / Update: Save your entries to include them in your SA108 return.
- Delete Entry: Use the red Delete link inside a modal to remove a specific record.
- Cancel: Discard changes and return to the overview.